Update · 7 October 2026
The Westpac–Melbourne Institute Consumer Sentiment Index, released on 6 October, fell 4.7% to 80.4 from 84.4 in September. The consumer-sentiment event in the week-ahead table below has now occurred. The original market scoreboard remains a snapshot of Friday 2 October.
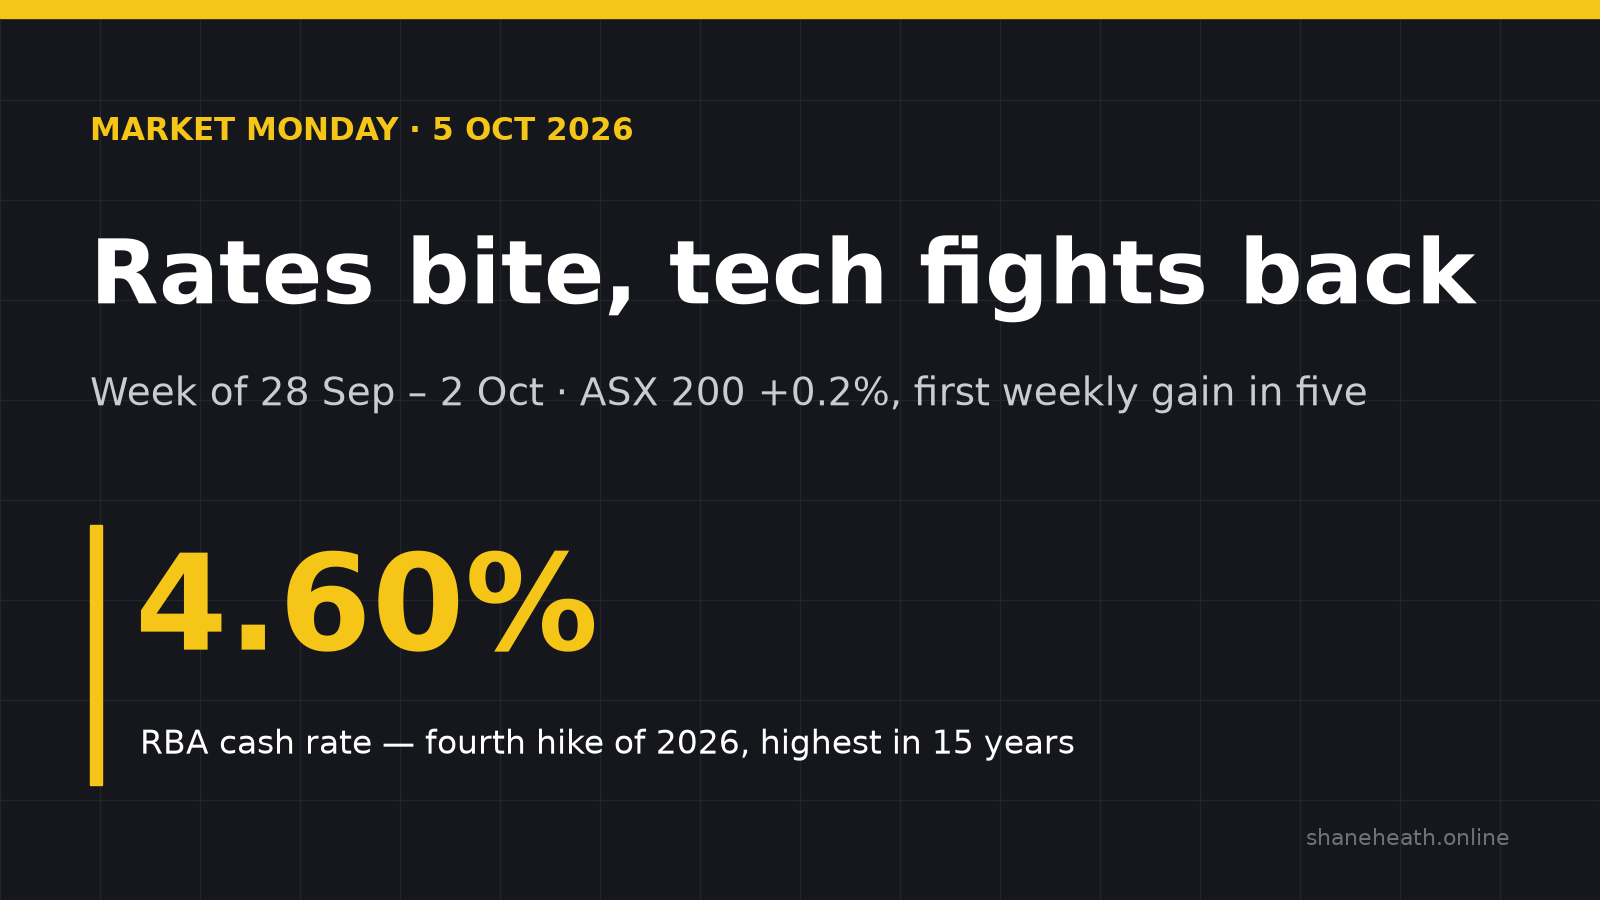
The RBA hiked again, bond yields hit 24-year highs and the ASX dropped 2% in a day — yet still finished the week in the green, its first weekly gain in five. Tech and defence carried it. Here's what happened, why it matters, and what to watch this week.
Last week's watch-list, scored
Last Monday I flagged three things to watch. Here's how they played out.
| Watch item (28 Sep) | What happened | Verdict |
|---|---|---|
| Yields and oil — could a 10-year near 5.2% stall the AI rally? | The US 10-year pushed through to 5.34% midweek, its highest since 2002, and Brent held above US$100. The S&P 500 slipped 0.3% — but the Nasdaq still rose and Nvidia hit a record. | Bent, not broken. The rally narrowed further rather than stalling. |
| Autonomy calendar — the US Air Force's Collaborative Combat Aircraft provider decision | No selection was reported in the sources reviewed this week. Defence-tech demand showed up in Australia instead: Codan +24% in a day, DroneShield +13% for the week. | Pending. Carried forward. |
| Supply risk — the January 2027 rare-earth sourcing deadline for drone makers | No change to the deadline. Lynas fell almost 10% after a broker downgrade, a reminder that "strategic" doesn't mean "safe". | Live. Carried forward. |
The scoreboard
| Market | Friday 2 Oct close | Week |
|---|---|---|
| ASX 200 | 8,682.1 | +0.2% (first weekly gain in five) |
| S&P 500 | 7,722.7 | −0.3% |
| Nasdaq | 27,190.9 | +0.5% |
| Dow Jones | 51,177.0 | −1.3% |
| Nikkei 225 | 68,309.5 | +2.9% |
| Hang Seng | 23,972.3 | −2.2% |
| FTSE 100 | ~10,452 | −2.2% |
| AUD/USD | ~69.5 US cents | down — fourth weekly fall |
| Gold | ~US$4,140/oz | down — −7.5% over the month |
| Brent crude | US$102.25/bbl | flat |
| Iron ore (61% Fe) | US$92.35/t | soft |
| Bitcoin | ~US$84,700 | down |
1. The RBA goes again
On Tuesday 29 September, the Reserve Bank lifted the cash rate 25 basis points to 4.60% — its fourth hike of 2026 and the highest rate in 15 years. The decision was unanimous.
Governor Michele Bullock pointed at something new: the AI boom itself. She said AI investment is adding to demand at a time when the economy is already stretched.
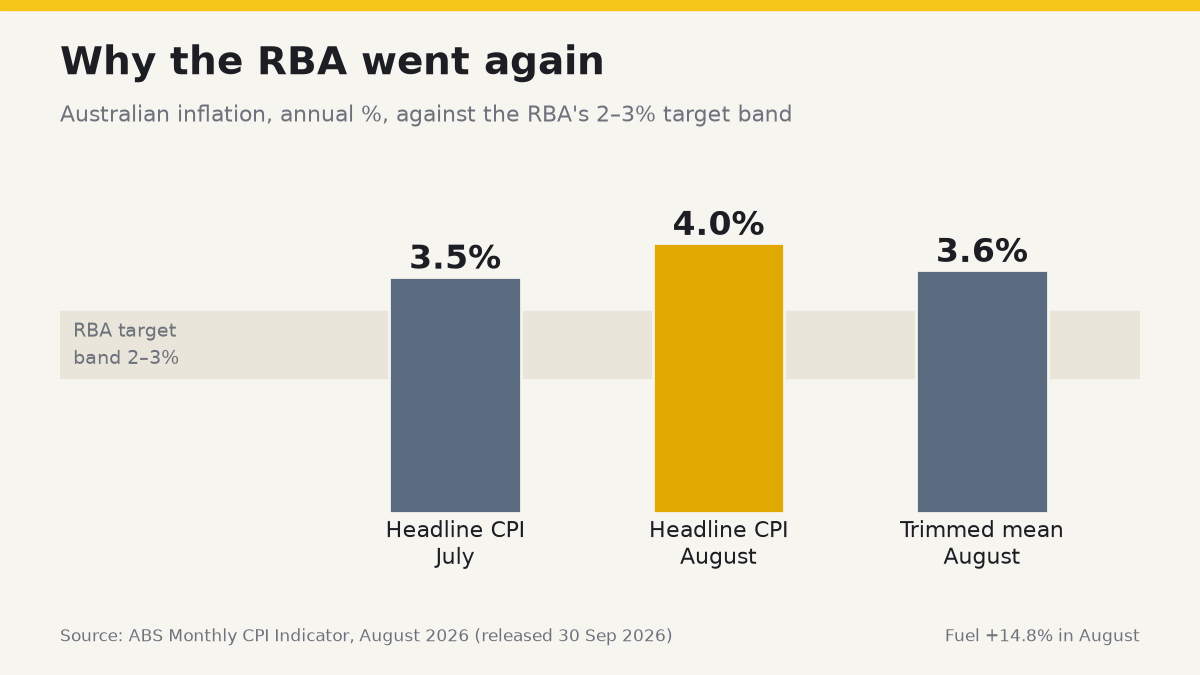
The next day's data showed why the Board is nervous:
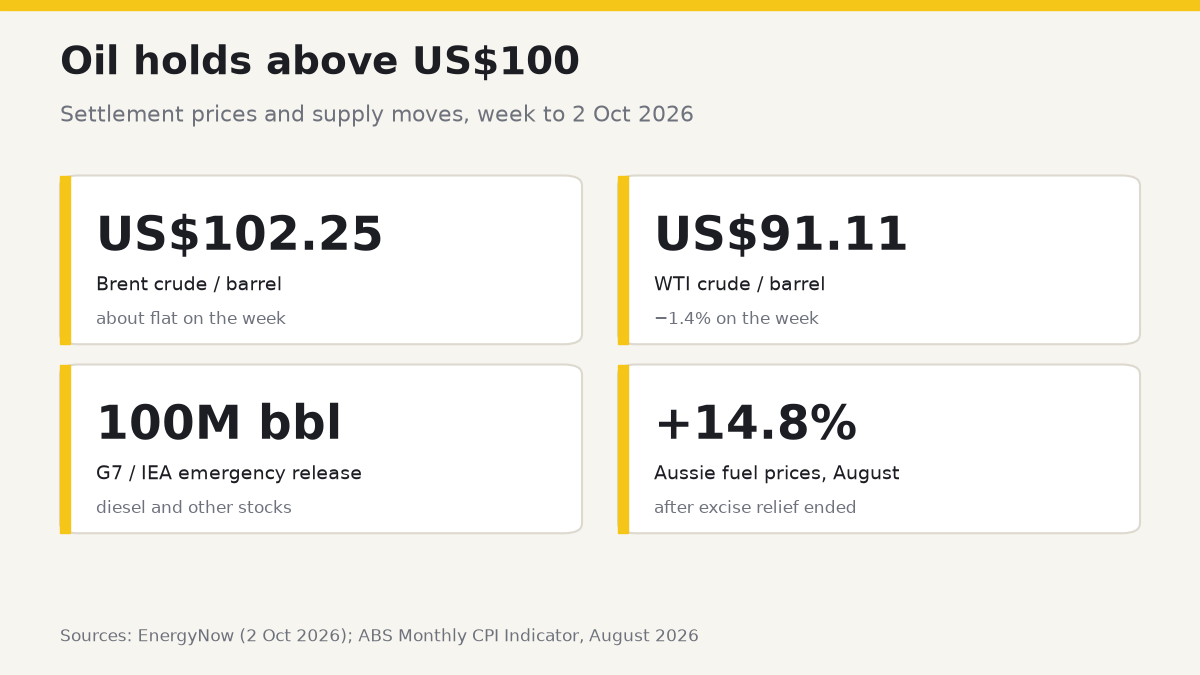
- Inflation rose to 4.0% in August (from 3.5% in July). Fuel jumped 14.8% in a month after excise relief ended.
- Underlying (trimmed mean) inflation held at 3.6% — still well above the 2–3% target.
- Household spending was flat for the month but up 6.8% on a year ago.
- Building approvals fell 6.1%, dragged down by a 21% drop in apartments.
- Job vacancies slipped to 325,000 — 31% below their 2022 peak. The jobs market is cooling, slowly.
What it means for you: mortgage holders are absorbing a fourth rise this year. Markets currently put only about a 1-in-5 chance of another hike at the next meeting on Melbourne Cup Day, 3 November — but the RBA has said it will move again "if needed".
2. Thursday's 2% scare
On Thursday 1 October, the ASX 200 fell 2% in a single session to 8,614 — its lowest since June. More than $50 billion in value disappeared and every sector closed red.
The trigger wasn't local. Higher oil prices pushed global bond yields up sharply:
- The US 10-year Treasury yield touched 5.34% — its highest since 2002.
- Australia's 10-year yield hit about 5.40%.
When safe government bonds pay over 5%, shares — especially property and other rate-sensitive stocks — look less attractive. That's the whole story of Thursday in one sentence.
3. Tech and defence fight back
Then the rebound. The ASX tech sector rallied about 7% for the week, its best run since August.
- Codan (CDA) jumped 24% in a day to an all-time high after guiding to first-half profit of at least $160 million — more than double last year. Roughly half its communications revenue now comes from conflict regions.
- Data#3 (DTL) rose 14% after forecasting first-half profit up about 40%, well ahead of analyst expectations.
- DroneShield (DRO) gained 13% for the week on contract wins.
- Megaport, WiseTech and Xero all rallied hard on Friday.
On the losing side, lithium miner Liontown (LTR) fell 15% after its mine expansion bill blew out, and Lynas dropped almost 10% after a broker downgrade.
Deal watch: Gold Fields has made a takeover approach for Northern Star, which is reviewing it. Warburg Pincus raised its bid for Ingenia to $5.25 a share.
4. Wall Street: weak jobs, record Nvidia
- US jobs disappointed. Only 29,000 jobs were added in September versus about 90,000 expected. Unemployment ticked up to 4.2%, and annual wage growth slowed to 3.0% — the weakest since 2021.
- The Fed blinked. After hiking in September, odds of another US rate rise in October collapsed from about 64% to about 16–25%. Markets now eye December instead.
- Nvidia hit a fresh record, valuing the company at about US$5.7 trillion. The Nasdaq was the only major US index up for the week.
- Tesla rose about 5% on better-than-expected deliveries; Nike fell about 5% on weak revenue and layoffs.
5. Commodities: oil stays above $100
- Brent crude held above US$100 despite a coordinated 100-million-barrel emergency stock release by G7 and IEA nations. Middle East tensions and China suspending fuel exports kept a floor under prices.
- Gold slipped for a second week. Rising bond yields make a non-interest-paying metal less attractive — it's down about 7.5% over the month.
- Iron ore stayed soft (around US$92/t) with China on its Golden Week holiday.
- The Aussie dollar fell for a fourth week, to about 69.5 US cents, despite the RBA hike. The gap between Australian and US interest rates has narrowed to almost nothing, so the hike gave the currency little lift.
6. The big picture
Three themes ran through the week:
- The bond market is in charge. Yields at 20-year-plus highs are setting the tone for every other asset.
- Rates are diverging. The RBA is still hiking into 4% inflation; US jobs data is pushing the Fed toward a pause.
- A narrow rally. Gains are concentrated in AI, tech and defence names. Narrow rallies can run — but they're fragile when yields jump.
This week: what to watch (5–9 Oct)
| Day | Event | Why it matters |
|---|---|---|
| Tue 6 Oct | Westpac consumer sentiment (Oct) | First read on how households took a fourth rate hike |
| Wed 7–Thu 8 Oct | Harvey Norman goes ex-dividend (13c, fully franked) | Income investors' date |
| Thu 8 Oct, ~5am AEDT | US Federal Reserve minutes (September meeting) | How keen is the Fed on more hikes after the jobs miss? |
| Thu 8 Oct | China's markets reopen after Golden Week | Watch iron ore and miners |
| Thu 8 Oct | Firmus IPO bookbuild | A test of appetite for AI-infrastructure floats |
| Fri 9 Oct | US consumer sentiment (prelim.) | US household mood |
| All week | Northern Star / Gold Fields takeover talks | A potential mega-deal in Aussie gold |
Coming soon: RBA minutes (13 Oct), US inflation (14 Oct), Australian jobs data (15 Oct) and Australian September inflation (late Oct).
Next week's scorecard
Next Monday, I'll check these calls against what actually happened:
- Does the ASX 200 make it two up-weeks in a row?
- Does the US 10-year yield stay above 5.2% — and does the AI rally keep narrowing?
- Does Brent hold above US$100?
- Does the Aussie dollar break its four-week losing streak?
- Carried forward: any Air Force CCA decision, and any shift in the January 2027 rare-earth deadline.
Market Monday is commentary and observation, not investment or trading advice. Figures are as reported at Friday 2 October close; some sources differ slightly on exact levels.
Sources & further reading
- Trading Economics — Australia stock market
- Small Caps — weekly wrap (2 Oct)
- Market Index — Friday wrap
- ABC — 1 Oct sell-off live blog
- IBTimes AU — Codan
- IBTimes AU — Data#3
- IBTimes AU — Liontown
- FNArena — Next week at a glance (5–9 Oct)
- Yahoo Finance — 2 Oct markets and jobs report
- T. Rowe Price — global markets weekly update
- Advisor Perspectives — S&P 500 snapshot
- Yahoo Finance — Fed hike odds (1 Oct)
- Trading Economics — Japan, Hong Kong, UK, AUD, Gold
- EnergyNow — oil week (2 Oct)
- MMi iron ore index (2 Oct)
- CryptoTimes — Bitcoin (3 Oct)
- RBA — monetary policy decision (29 Sep)
- ABS — CPI rose 4.0% in the year to August 2026
- ABS — Building approvals; Job vacancies
- Newsquawk — weekly calendar (4–9 Oct)
The audio edition
The narration presents the original weekly edition. The dated update above was added on 7 October.
Written by Shane Heath. Narrated by Maren Solberg · 12:59. AI-generated narration.